Cost of Living in Decatur, Alabama: What a $320,000 Home Really Costs Each Month
Cost of Living in Decatur, Alabama: What a $320,000 Home Really Costs Each Month
Short answer: For a $320,000 example home in Decatur, Alabama, the mortgage, property taxes, homeowners insurance, and average utilities add up to about $2,294 a month. That assumes 20% down on a 30-year conventional loan at 7.375%, the rate when I recorded this. It's a housing subtotal, not your full cost of living. Maintenance, internet, groceries, sales tax, and your commute all come on top of it.
Everybody talks about how affordable Alabama is. And if you're moving to Decatur from somewhere with high property taxes, your first tax bill here might make you wonder if somebody left off a zero.
But a low tax bill and a low monthly budget aren't the same thing. So I took a realistic Decatur home and ran every monthly number I could pin down: the mortgage, the taxes, the insurance, and the utilities. Here's where the money goes and what I'd check before you buy.
The example home
Watch this part → https://youtu.be/R6vEj7Xdplg?t=48s
To keep this grounded, I started with our local MLS. In the Eastwood Elementary attendance zone in Decatur, single-family homes that sold between January 1 and October 28, 2026 had a median of about 2,100 square feet and a median sales price of $317,000.
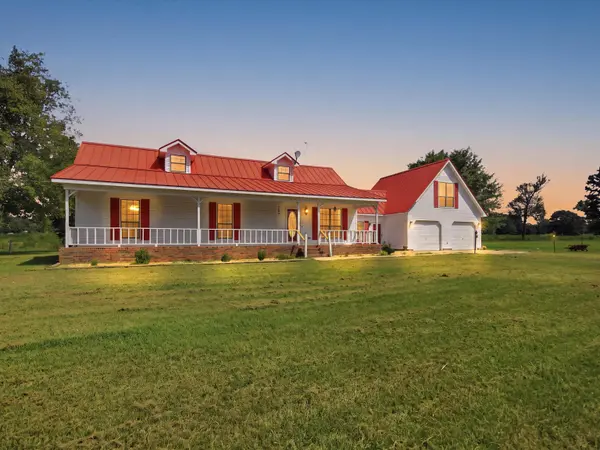
So the example home is $320,000, with 4 bedrooms, 2.5 baths, about 2,100 square feet, and built around 1985. At that price, the buyer is usually moving up or downsizing, not buying a first home. That matters because those buyers typically bring equity from the house they're selling.
One thing to keep in mind while you shop: two houses with the same square footage aren't the same value. What's been updated, what hasn't, and what needs work soon all change the math. The purchase price is where the calculation starts, not where it ends.
The mortgage: about $1,727 a month
Watch this part → https://youtu.be/R6vEj7Xdplg?t=118s
Local lenders I talked to said most buyers at this price are putting money down from a previous home, so I used 20% down, a 30-year conventional loan, and a 7.375% rate. That puts principal and interest at about $1,727 a month.
This is an example, not a mortgage quote. Your financing could look very different, and with less down your loan could require mortgage insurance, which this example doesn't include.
Property taxes: about $84 a month
Watch this part → https://youtu.be/R6vEj7Xdplg?t=162s
This is usually the first question I get from people moving here from out of state. For the example home, I used an annual property tax bill of about $1,000 with the homestead exemption filed. Spread over 12 months, that's about $84 a month. If you're paying a lot more than that now, it makes a real difference.
Two cautions. First, don't assume the seller's tax bill will be yours. The number you use should reflect your situation, not what the current owner has paid for years. Check with the appropriate county revenue office about the property, your eligibility for exemptions, and any other requirements.
Second, the homestead exemption doesn't happen automatically when you close. You have to file for it yourself. If you skip it, you won't get the discount.
Homeowners insurance: check it early
Watch this part → https://youtu.be/R6vEj7Xdplg?t=216s
Don't leave insurance until the week before closing. It's gotten harder to estimate over the last couple of years, and the small number under an online payment calculator probably isn't right.
For this video, I called a local insurance agent I work with a lot and asked for a typical number. He told me there isn't really one anymore. Insurers look at so many factors that two houses on the same street can get very different quotes. He did give me a range: on a typical $350,000 house, somewhere around $2,000 to $3,000 a year, or roughly $170 to $250 a month, and it can run higher.
The two things that move the price the most are the age of the roof and your insurance score. That score is built partly from your credit history, partly from claims you've filed, and partly from claims filed on the home you're buying. For the example home, I used $2,500 a year, which is about $208 a month.
When you get quotes, ask what coverage you're getting, what the deductible is, and whether there are limits you need to understand. Give the insurer accurate details, including the age of the roof and major systems. If you're choosing between two homes, get a quote on each one. Don't assume they'll match.
Utilities: one bill through Decatur Utilities
Watch this part → https://youtu.be/R6vEj7Xdplg?t=350s
I don't want to hand you a national average here. Decatur usually has reasonable utility rates, partly because power comes through TVA. Most of your services also run through one provider, Decatur Utilities, so you get one bill, one setup call, and one number to call for service.
Before filming, I talked with several homeowners in the same area who have houses similar to the example. Averaged across a full year, their monthly bill was about $275, so that's the planning number I used.
Your bill will depend on how you live. You might keep the thermostat at a different setting, have more people in the house, or be home all day. Ask the seller for 12 months of utility bills, not just one. And look at the house itself: the age of the heating and cooling system, the insulation, and the windows.
The monthly subtotal: $2,294
Watch this part → https://youtu.be/R6vEj7Xdplg?t=447s
Mortgage principal and interest: $1,727
Property taxes: $84
Homeowners insurance: $208
Average utilities: $275
Estimated monthly subtotal: $2,294
I call that a subtotal on purpose. It covers the expenses above, not everything you'll spend owning the house. You still need room for maintenance, repairs, internet, HOA dues if there are any, and other property-specific costs. An air conditioner doesn't care that you just spent your reserves moving to Decatur.
How much cushion makes sense depends on the house: what the inspection turns up, what's already been replaced, what's coming due soon, and what you can handle yourself.
Two more notes. Taxes and insurance are spread over 12 months here so you can compare them, but they're usually part of your mortgage escrow payment, so don't count them twice. And none of this includes the cash you'll need upfront: your down payment, closing costs, and any work the house needs right away.
What the subtotal leaves out
Watch this part → https://youtu.be/R6vEj7Xdplg?t=535s
Owning a home in Decatur and living in Decatur are two different budgets. Sales tax is one example. The general combined rate in Decatur is 9%. If you're coming from a place with different rates, or one that doesn't tax groceries the same way, put that in your comparison. It depends on your spending, so it isn't in the housing subtotal, but it's still money leaving your household.
The same goes for transportation. Where will you work, how often will you make that drive, and what does your normal week look like? Then add groceries, dining out, childcare if it applies, and everything else your household spends.
So is Decatur affordable for you?
Watch this part → https://youtu.be/R6vEj7Xdplg?t=596s
Don't decide based on one listing price or someone telling you Alabama is cheap. Take a house you'd actually consider and run the numbers: financing that fits your situation, verified taxes, an insurance quote on that exact house, the utility history, and the condition of the home. Then leave room for the things a mortgage calculator doesn't show.
You may find Decatur gives you exactly the balance you're looking for. Or you may decide a different house, price range, or town fits you better. Either way, I'd rather you know before you buy. The real question isn't whether Decatur is affordable. It's whether this move makes financial sense for you.
Frequently Asked Questions
How much does it cost per month to own a home in Decatur, Alabama?
For a $320,000 example home with 20% down on a 30-year loan at 7.375%, the mortgage, property taxes, homeowners insurance, and average utilities came to about $2,294 a month. That's a housing subtotal. It doesn't include maintenance, internet, groceries, or transportation.
Are property taxes low in Decatur, Alabama?
Compared with many states, yes. The example home used an estimated $1,000 a year, about $84 a month, with the homestead exemption. You have to file for the homestead exemption yourself, and you should confirm the numbers for your property with the county revenue office.
How much is homeowners insurance in Decatur, AL?
A local insurance agent estimated about $2,000 to $3,000 a year on a typical $350,000 home, and it can be higher. Roof age and your insurance score move the price the most, so get quotes on the specific house you're buying.
Run the numbers on your own move
If you're thinking about moving to Decatur, I'm happy to walk through a house you're considering and what it would really cost you each month. Book a quick 15-minute call: https://calendly.com/cpeters-real/15-min-real-estate-consult. Or call or text me at 256.476.4201.
Before you decide, it's worth knowing more than what Decatur costs. Watch 5 Things Nobody Tells You About Moving to Decatur next: [ADD LINK: 5 Things Nobody Tells You About Moving to Decatur]
Sincerely,
Clint Peters
REALTOR® | Real Broker
256.476.4201
The figures in this post are examples for one hypothetical home. They aren't a mortgage quote, tax assessment, or insurance quote.
Categories
Recent Posts